Systematically evaluating market cap restaked avs infrastructure is now an essential competency for venture funds, research analysts, and institutional liquidity allocators. The rise of restaking protocols (pioneered by EigenLayer and expanded across Symbiotic, Karak, and multi-chain restaking hubs) created a fundamental paradigm shift: instead of requiring every new decentralized network to bootstrap its own multi-million-dollar Proof-of-Stake (PoS) validator set and native token from scratch, developers can lease pooled economic security directly from existing base layers.
These networks—termed Actively Validated Services (AVS)—range from specialized data availability layers and decentralized sequencer sets to zero-knowledge coprocessors, oracle feeds, and cross-chain bridges. However, assessing the intrinsic valuation and realistic market capitalization of native AVS tokens presents unique financial challenges. Unlike standalone Layer 1 networks where market value is driven by sovereign monetary premium, an AVS is fundamentally a utility and fee-generating service layer anchored to borrowed economic capital.
The Fundamental Shift: Borrowed Security vs. Native Market Cap
In classical blockchain economics, a network’s market cap directly dictates its economic security. If a standalone PoS network has a token market capitalization of $100 million, an attacker with roughly $67 million in capital could execute a Byzantine attack to compromise consensus.
AVS networks invert this relationship:
-
Security Decoupling: An AVS secures itself using billions in pooled, restaked collateral (such as restaked ETH, liquid restaking tokens, or institutional liquid assets). The economic cost to corrupt the AVS is defined primarily by its restaked pool, not the market cap of its native token.
-
Dual-Token Coordination: Many AVS architectures deploy a dual-quorum validation structure. Transaction validation requires sign-off from both restaked ETH nodes (providing baseline economic immutability) and native AVS token stakers (who govern application-specific parameters, subjective slashing conditions, and protocol upgrades).
Consequently, native AVS tokens cannot be valued solely as security collateral; they must be modeled through the lens of cash flow generation, capital efficiency multiples, and protocol governance value.
Core Valuation Framework: Three Quantitative Pillars
To construct a defensible valuation model for an AVS network, institutional analysts combine three quantitative lenses:
1. Discounted Cash Flow and Fee-Burn Multiples
At operational maturity, an AVS must generate sustainable revenue paid by dApps and end users utilizing its services (such as fees paid for cryptographic proofs, data throughput, or cross-chain state relays).

2. Capital Efficiency and Security Rental Ratios
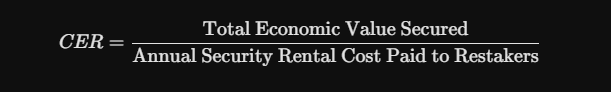
Traditional PoS blockchains face a massive “cost of capital” because they must print high annual inflation to incentivize validators to lock up native tokens. An AVS leases capital that is already earning yield elsewhere, paying only a modest security rental premium (often 1.5% to 4% annualized).
Analysts calculate the Capital Efficiency Ratio (CER):
3. Slashing Attribution and Governance Premium
When an AVS implements native token slashing for subjective or application-specific faults (e.g., misreporting an off-chain data feed where algorithmic consensus cannot easily verify fraud automatically), the native token captures a critical governance and coordination premium. If controlling 51% of the native AVS token quorum allows an actor to reallocate protocol revenue or alter core slashing parameters, the token’s market capitalization must trade at an equilibrium that exceeds the potential payoff of malicious governance capture.
Comparative Valuation Matrix Across AVS Sectors
| AVS Vertical | Primary Fee Revenue Model | Security Capital Requirement | Market Cap Multiple Driver |
| Data Availability (DA) | Pay-per-megabyte data throughput fees | High (Requires massive economic safety margin) | Long-term L2 rollup adoption & bandwidth utilization |
| ZK Coprocessors | Per-proof verification compute fees | Moderate (Verifiable math limits fraud vectors) | Off-chain compute demand from intensive dApps |
| Shared Sequencers | Priority transaction fees & MEV share | Extreme (Vulnerable to cross-chain double spends) | Settlement volume across connected modular rollups |
| Decentralized Oracles | Subscription API access & per-query fees | High (Directly underwrites DeFi collateral values) | Total DeFi TVL secured across partner chains |
Evaluating Structural Risks and Multiple Compression
When modeling market capitalizations for early-stage AVS tokens, analysts must apply risk discounts to account for structural restaking bottlenecks:
-
Operator Churn and Cascading Unbonding: If yield spreads narrow, operators and restakers can rapidly reallocate capital to higher-yielding alternative services, causing sudden drops in secured TVL.
-
Dual-Slashing Exposure: Unhandled edge cases in complex smart contract slashing logic can trigger unjustified capital loss, causing immediate panic un-staking across both native and restaked asset pools.
-
Attestation Oversaturation: If an AVS shares a validator set with dozens of other networks, validator hardware can experience performance degradation during network spikes, resulting in missed attestations and compressed fee yields.
The Bottom Line
A structured methodology for evaluating market cap restaked avs infrastructure shifts the investment framework away from speculative L1 tokenomics toward enterprise software and infrastructure metrics. By auditing real protocol fee throughput, measuring capital rental efficiency against pooled restaked collateral, and quantifying governance capture thresholds, allocators can distinguish resilient, cash-flow-generating validation layers from overvalued, emission-subsidized networks.